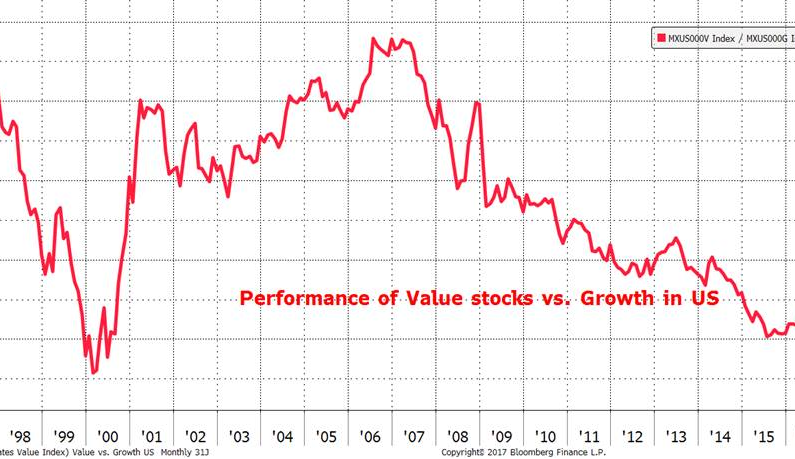
So there’s been a bit of a recovery in stock markets so far this year after a dismal December. It’s not very surprising and it does seem to lack conviction.
The year so far has been marked mainly by official downgrades to global economic growth, accompanied at times by “Game of Thrones” rhetoric and headlines such as “Darkening Skies” (courtesy of The World Bank).
We are likely to see more of these downward macro revisions – institutional economists are very aware of what their peers are saying, and don’t reverse direction easily. Other issues which have unnerved markets in recent months are still on the table – end of supportive Central Banks, health of China’s economy, increasing trade friction etc. These are guaranteed to resurface.
Yes, markets may offer better value than 3 months ago – but valuation alone is never enough.
A slower pace to economic growth is not a catastrophe. In fact sustainable slower growth which doesn’t force the pace of inflation or interest rates is quite a benign backdrop for equity markets.
It’s the degree to which corporate profit forecasts may be out of synch with that economic reality that really matters.
There is quite a strong correlation between analyst revisions to their forecasts and stock market direction.
It can be hard for markets to make progress in the face of a storm of analysts downgrades. The next few weeks will see profit forecasts being revisited on the foot of quarterly numbers and company updated guidance. As far as we can tell, this is the next big thing for markets, and at least it’s grounded in company fundamentals and not determined by the next tweet from 1600 Pennsylvania Avenue.
Analysts did move at the end of 2018 to rein in their numbers for the outcome for 2019. Today the consensus forecast for growth in global profits this year is just under 6%. 2020 numbers at just over 10% do seem a bit elevated still. The key question is whether that 6% figure for 2019 comes under further pressure. There will be wall to wall coverage of the actual quarterly announcements, but remember this is a highly choreographed event with companies guiding the stockbroking analysts as to how close their forecasts are to the likely outcome. There is little real predictive power in the exercise.
To make sense of markets it is better to focus on the company statements (like Colgate who last week spoke of profits actually being lower in 2019 than 2018) and critically whether analysts take the red pen to their forecasts.
If we weather that near term storm then the possibility of a Fed pause, perhaps a softer US dollar, and subdued bond yields would all provide support for stocks.
 We are smack bang in the middle of the “market outlook 2019” season. Despite the fact that economic and market fundamentals don’t really recognise the Gregorian calendar, economists, strategists, commentators et al, rush to give their views on what the next 12 months holds – usually conveniently forgetting what they may have said at the start if 2018!
 What do you think? Do they know their Verdi from their
Vardy?, Van Gogh from Van Morrison, or their Rigoletto from their cannelloni?
Hard to know really!
But this culture thing seems to be getting more and more attention.
In Ireland the Central Bank has been devoting a lot of resources to this issue
and getting the banks to refresh/redefine/find their appropriate culture.
My initial reaction used to be that this type of thing was a
bit waffly, with little real world application. Management consultants immersed
themselves in these concepts, and for a reasonable fee their clients could dip
a toe in, as required.
But if we strip away a lot of the jargon and think of
culture as just being “the way we do things around here” (Bower), I think it
becomes more meaningful in an asset management context, and should be
considered in evaluation, selection and review of managers.
Towers Watson and Roger Urwin have been flying the flag on
this for many years. Since the early 1990s it has been a critical component in their
formal manager evaluation. For them, culture is a unique ingredient in
generating alpha and a bedrock on which a competitive advantage is sustained
over a long term. They have published good research on the topic, seeking to
define and measure what constitutes culture in an asset management context.
This is by no means an exact science. Factors involved will
typically include leadership, ownership, procedures, policies, diversity, respect,
remuneration etc.
Should we care? – or should we only care about investment
outcomes.
Positive culture should underpin alpha generation and
importantly (in my view) its persistence. However there my be times when strong
performance can disguise a weak culture. Equally weak performance can
exacerbate culture issues.
How does a solid asset management culture deal with
disappointing performance. I read one of GMO’s quarterlies recently where they
spoke about the importance of “crying over spilt milk”. This means when things
go wrong, try and understand why, and see what might be done better. Other
managers speak of having a WWW (what went wrong) wall, noting poor investment
decisions and focussing solely on the learning points. I think that
acknowledging poor performance (because it will happen!) is a necessary and
positive aspect in a good asset management culture. Investors and selectors
should view it similarly.
In recent weeks, a named lead manager for a large
blockbuster fund that had been through over 5 years of failure to meet targets,
suddenly announced a decision to leave. So I presume there had been 5 years of
meeting with clients justifying and defending performance and process again and
again. But conviction may have morphed into stubbornness and It seems to me
that the final outcome (manager departure) didn’t really do clients any
favours.
Maybe a culture where there was some crying over spilt milk
and learning opportunities sought along the way would have served clients (and
the asset manager) better.



 So anyway there I was listening to Morning Ireland, and this chap, who used to be big name in the ESRI, giving their highly thought of views every quarter, garnering acres of media coverage and attention, but now he’s saying “I’m not in the forecasting business anymore so I don’t have to pretend that I have a great sense of what’s actually going to happen”
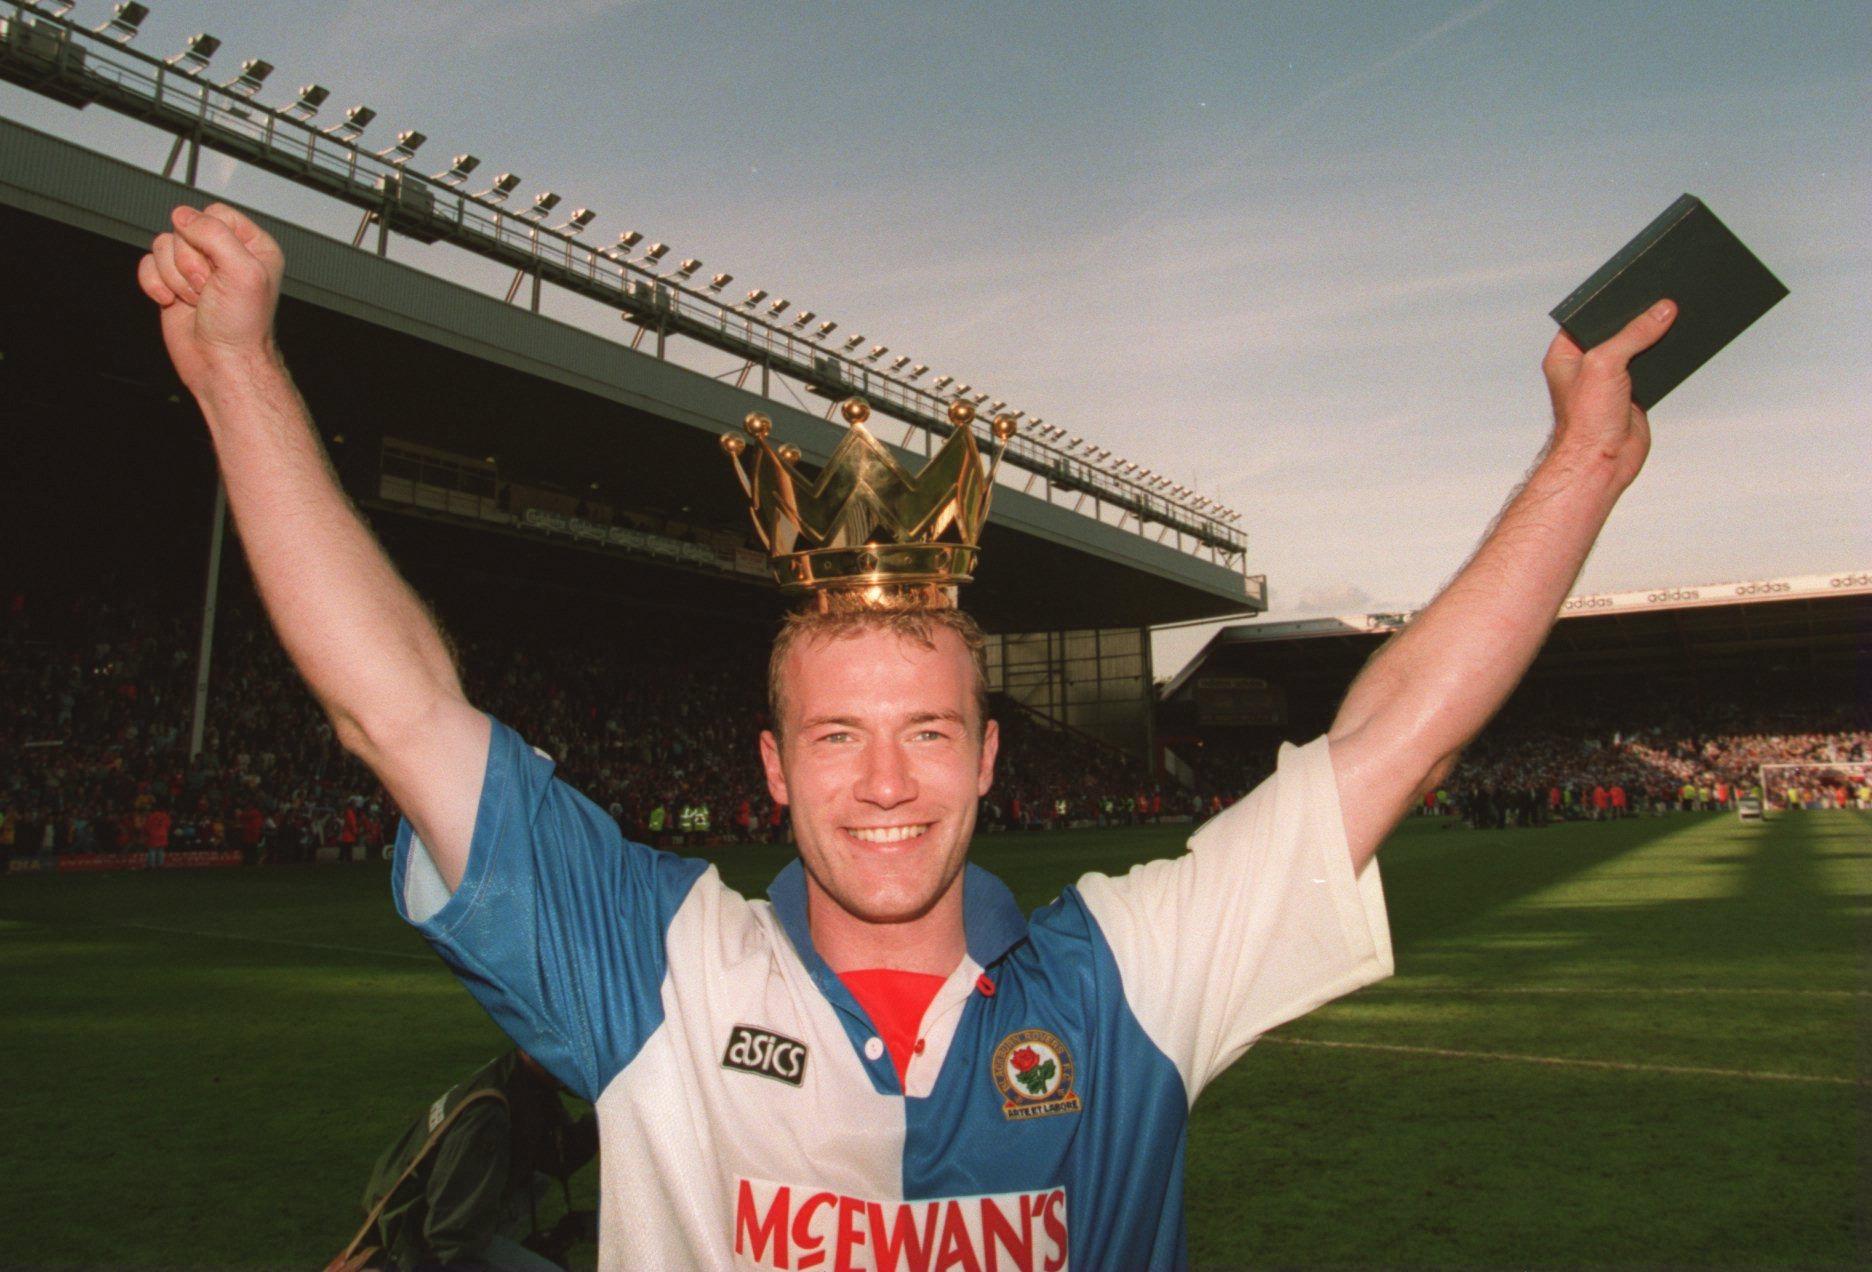 It was a Sunday evening in August way back in 1993. I was stood in that cauldron of emotion, United Park, where Drogheda United were playing Blackburn Rovers in a pre-season friendly. Blackburn were on the verge of greatness at that point. The first half was scoreless, which was a very good performance from Drogheda United. Kenny Dalglish wasn’t happy. He kept his team on the pitch at half time. Second half – no real change. The he sent on Alan Shearer who nonchalantly scored a couple of goals and basically ended the match. That late summer evening in United Park, I had seen a “game changer”