Language Lessons

It has been the economic surprise of 2021 and there are still voices on both sides of the argument.

Inflation has taken off as a concern for investors, consumers, producers and policy makers. The most recent number to grab headlines in the US was a staggering 6.2% – the largest since 1990. At the start of the year, 2.1% was the expected figure. 

The path to these price pressures is paved with supply chain delays, higher energy prices and higher wage bills in certain challenged sectors.

Central Banks built a defence by viewing all of these as “transitory” – which of course they may be. However the issue is when inflationary expectations are changed. Investors and manufacturers may have grown accustomed to living in a low inflation world – but there are signs of a change. The concept of “pricing power” is once again being mentioned. A recent survey in the US  has shown the proportion of  businesses thinking of raising prices is close to 50% – the highest since the early 1980’s. 

Inflation is certainly making its way into the corporate psyche and is front of mind for many CFOs and CEOs in US companies. If we look at the conference calls of the S&P 500 companies in this third quarter reporting season just ending, the percentage of companies citing inflation is over 60% –  double the norm of the past 5 years. Interestingly this hasn’t really fed through to lower profit margins yet.

Is this surprise in inflation numbers going to lead to a shock on interest rates?

For some commentators, the greatest crime a Central Bank can commit is “being behind the curve” i.e. not recognizing a change in the economic environment and having to catch up, but with the risk of inappropriate interest rate policies. 

Making this assessment is even trickier now as many Central Banks have made changes to their operating framework. Basically entities like the ECB and the Federal Reserve in the US are likely to tolerate higher inflation rates before they pull the rate trigger. In the US, for example, the Fed is looking to target average inflation over a time period rather than a spot level.

As we stand today, policy makers, certainly in the US and Europe, broadly hold on to the transitory narrative but there have been some interesting changes in language in the past few weeks. 

Closest to home, ECB chief Christine Lagarde now feels inflation will stay high for longer then she previously forecast. However she has pushed back on calls for rate hikes, sticking with the view that inflation will fall back somewhat in 2022. It is worth noting though that the ECB inflation forecasts are among the lowest around.

The actions of the Federal Reserve In the US probably matter most. Here we have had the most clearly communicated policy; namely of no action on rates until the jobs market was clearly improving. The chairman of the Fed, Jerome Powell, is reluctant to raise rates while there was still slack in jobs market, despite the surge in prices. The 6.2% number did have something of a “sticker shock” about it and the inflation numbers have been highly politicized. The situation has been complicated by the fact that we will see several changes in composition of the Fed board this year. And it is true that the most recent job numbers have been stronger.

Will this change the time-table? Comments from the Treasury Secretary Janet Yellen have become somewhat more neutral,  noting that Covid is likely to play a greater part in calling the shots on inflation and interest rates.

Most clear cut is the view of the Bank of England, which appears to be itching to hike rates. Andrew Bailey, Governor of the Bank, admits to being very uneasy about inflation being above target, suggesting action will be taken sooner rather than later. Bailey puts in very simply “We are in the price stability business”.

This more nuanced language we have heard may not change the sequence of rate rises – UK followed by US, followed at some point by the ECB – but may herald a change in time frame.

However beyond time frame, we are leaving a period when the interest rate policy of the major blocks was highly synchronised. This resulted in the very muted volatility we have seen in exchange rates – this too may change. 
Still Absolutely Not So Fabulous

Three years ago on this blog, I looked at Absolute Return Funds – funds that were still very much in vogue and in demand. They were the top selling fund type in 2016 and 2017 according to Investment Association figures. These funds typically offered cash plus 4% or more and the promise was that this would be delivered at a significantly lower risk level. Performance issues had already surfaced but the party-line for managers was to stick to their guns and rhetoric.

I thought it was a sector worth revisiting.

My conclusions three years ago were broadly that it was quite a challenging ask, lots of over-promise and under-delivery, and more than any other sector picking your manager was of key importance as there could be a wide range of returns.

The world has changed profoundly for Absolute Return funds and their managers. In the past two years (2019 and 2020), investors lost patience and this sector saw the worst redemptions in the industry. Redemptions were described as “brutal” by one manager. In 2019 and 2020, European domiciled Absolute Return funds saw over €40 billion head for the exit door. One very high profile fund went from £26.8 billion to £2.6 billion in 4 years.
The picture is similar with large pension funds though harder to map. While the overall allocation to Alternative Assets has grown, within the sector areas like Private Equity and Infrastructure have probably increased the most from a lower base. If we take hedge funds and multi-asset as a proxy for Absolute Return, in the very recent past they look to have lost ground. The picture is more stark in terms of future investing intentions. European pension funds plan to reduce allocation to hedge fund and multi-asset funds.
Many absolute return managers blamed the absence of volatility, and then, when there was volatility, it was the wrong type. Trends and asset moves became very short-lived and un-investable. Others blamed constant bull markets ,which reduced their shorting profits, even though relative performance is what determines absolute success in this sector.
I looked at the performance numbers for three of the major players in this space in the Irish market.

One YearFive YearTen YearVolatility
Fund A-0.7%1%2.6%4.6%
Fund B4.1%0.2%n/a5.9%
Fund C9.8%3.3%4.3%7.4%
Average Managed15.8%6.1%7.6%9.7%

                                                                                                (Source: Aon; Annualised %pa)


A few things stand out.


Performance as we know has been poor but also it’s hard to see any broad recovery in the sector numbers in the near term despite what the managers may have hoped for. It is also interesting that the best of the three is the one with the highest volatility level – edging closer to that of a standard managed fund. This is also reflected in CityWire statistics in the UK where the better performers in their Absolute Return sector display higher volatility levels. This would seem to point to the difficulty of earning high returns while only taking on lower risk.


How did the Absolute Return industry respond?

There have been a number of responses.
We have seen fund name changes and modification of investment objectives. For example this summer, a long standing Absolute Return fund morphed into a “Flexible Macro” fund.
We have seen fund closures and cash returned to investors. One industry leader closed a high profile fund recently in the face of desperate performance and massive redemptions.
We have also seen changes in the people actually managing the funds in the hope that new faces or a new approach would do the trick. This has meant both retirements and sackings.

There is still a large number of Absolute Return funds out there, and making a choice between managers is more important than allocating to the sector given the range of returns which remains a feature.
There is little evidence to suggest that using hundreds of analysts, steering groups, and ending up with thousands of holdings actually works any better.
There is still a role for uncorrelated asset classes in portfolio construction. Currently asset classes such as Private Equity or Infrastructure garner most attention.

An absolute return fund with genuine alpha generation potential can play a role but it would help if there was a true reset of expectations in terms of what cash plus returns can consistently be achieved.
The simple learning from the emergence of Absolute Return funds is that the link between risk and return has not been broken.

Emerging Markets – is it over?

Emerging Markets have long played a role In investment portfolios whether pension funds or retail investors. Investing in sometimes more “exotic” markets has been seen to be a way of tapping into higher returns while diversifying away risk.

Investors could have exposure to Coca-Cola bottlers in Argentina, software companies in India through to supermarkets in South Africa and all at (certainly in the early days) extremely attractive valuations. It became one of the most exciting themes in financial markets.

Emerging Markets (EM) as a term was recognised in 1981.

Investment fundamentals were based on super normal growth prospects due to features such as new wealthier middle classes across Latin America and Asia increasing the quantity and quality of their consumption at pace.

There were periods when EM provided turbo-charged returns to investors, and came to be seen as a separate asset class in itself.

Is the case for such investment still intact?

There are two aspects to this question – the near term impact of Covid and the longer trends that drive Emerging Market dynamics.

Pandemics increase whatever inequalities exist pre-crisis. Today poorer access to vaccines and weaker policy responsiveness are causing EM economies to slip back.

As recently as July, the IMF increased its growth forecasts for advanced economies while revising down the figures for the developing world. Excluding China, Emerging Market growth in 2022 will be significantly lower than for advanced economies. Rather than catching up with advanced economy growth rates, many emerging economies are slipping back and some run the risk of falling onto fragility.
This softer economic picture is compounded by policy responses such as interest rates. While developed market economies are still very much in the “lower for longer” phase, 50% of emerging market central banks have already raised interest rates.

Covid in EM will cast a long shadow in many forms.
Longer term productivity of human capital will be impacted by pandemic-driven loss of schooling time and again EMs have fared worst. In 2020 children in advanced economies missed about 15 days of school; in EM economies this figures was closer to 50.

So it’s clear Covid is a serious set-back for emerging economies. But in many ways it only exposed existing vulnerabilities.
The slipping relative economic growth picture for EM was already in place. Following the financial crisis, economic growth rates for developed economies fell by 50%, but for EM economies the drop was a more precipitous 70%. 2013 was the probably the last year when EM economies had an outstanding growth advantage.

When EM economies had their days in the sun, there were several more ingredients which supported the market explosion – interest rates were generally on a downward track, commodity price rises were supportive and trade globalisation moved up a gear.
Emerging economies exports surged as trade went from 39% of world GDP in 1990 to over 60% by 2008.

Throughout the period from 1980’s onwards, another very supportive force was a move to more liberal democracies especially in Latin and South America. The prospects for greater political stability, less corruption and higher and fairer incomes could only be positive for investors.

Against this backdrop and with attractive valuations, global pension funds and others rushed to capture this frontier market premium and drive markets up.

However today, many of these longer term trends are challenged.

Both near term and longer term, EM economic growth prospects are poorer. The share of countries where output per head is superior to the US continues to fall. Another feature is that from here interest rates cannot fall further and some policy makers are already in hiking mode. 2023 may see US rates themselves move up. Another positive pillar for EM in the past – globalisation – may have stalled and because of Covid may shift into reverse.
We’ve also seen a pause in the drive to more liberal and accountable regimes. The humanitarian disaster in Brazil, civil unrest in South Africa and roll back of fiscal reforms in Chile are all global signposts of this change of direction.

Investors need to take on board these longer term trends, as well as the short term impact of the global pandemic, when considering investing in Emerging Markets. This more challenging environment is visible in the market performance of EM. Over the last 10 years, global equities are up by 11% per annum; the figure for EM is 3.6%.

But as well as the “why” of investing, there is the question of the “how”.

Broad EM indices bring a number of issues. They can be highly concentrated. China for example accounts for 35% of the total index. This is up from 7% in 2003 . In the same period Mexico has gone from 8% to 2%. Concentration is also high at stock level. The top 3 stocks account for 16% of the index and the broad technology sector accounts for more than a third. This is not the widely diversified index that it may have been in the past. Events and policy decisions in China (such as the recent crackdown on educational tech companies) will have a profound impact on many EM benchmarks.

Are EM stocks cheaper? Yes – but the gap is nowhere as big as it was when interest in EM was very much in a growth phase.

There will always be room in investor portfolios for stocks and sectors that offer growth potential at reasonable valuations. For many years this was the EM investment case. Today the sector faces as many headwinds as tailwinds and needs to be an active decision not just a default response based on investment muscle memory.

US Economy 2021: Fire and Ice

Where does the US Economy go from here?

There are two clear views – and they are almost diametrically opposed to one another.

And we are seeing the data swing from supporting one view to the other, on an almost daily basis.

One view is that too much money is being pumped into the economy, that inflation is now embedded at worryingly high levels, the Federal Reserve is behind the curve and we need interest rate hikes soon.

The other is growth has already peaked and the negative impact of the new Delta variant is yet to be seen in economic forecasts, and that we may be facing into a slowdown.

What are the facts?
Inflation today is indeed well above target, and has policy makers on edge. Data for June shows prices up over 5% compared to 12 months ago. The US Central Bank’s target is 2% on average. Even taking out some of the more volatile elements like food and energy we still have a 4% inflation rate in the US today. By contrast here in Ireland we’re looking at 1.6% and price increases of about 2% for the Euro area as a whole.

The key question – is it temporary? That’s certainly the view of the administration and the Federal Reserve. They believe that over the coming months improving supply chain bottle-necks and continued re-opening will ease this price pressure. And many of the price increases are simply recapturing ground lost during the pandemic. This means that the Federal Reserve, despite admitting to being somewhat surprised by the higher prices, can stick with its low interest rate policy. However the inflation debate is becoming increasingly politicised as Republicans highlight the rising cost of living for ordinary Americans and raise concerns over a stagflating economy. We should expect inflation to move up the political agenda. Importantly though surveys show that while consumers do expect higher prices in the near term, longer term expectations remain anchored at just over the 2% mark.

And what about economic growth? Figures for the second quarter of this year showed a very robust 6.5% rate of growth. However this was actually lower than forecasters had pencilled in. Consensus was expecting the number to be over 8%. While the US economy is now back to its pre-pandemic level, it is also past its peak rate of growth for this cycle.

Looking into the second half of 2021, we will see a waning of the fiscal package that has been supporting workers and businesses through the crisis. There has also been a knock to consumer confidence from the current surge in prices. This paints a less positive picture for consumer spending overall. But now added into this, is the impact of the Delta variant and the roll back we are seeing in the reopening process. Hospitalisations are back to mid-February levels. We have seen some companies push back on when they would look for staff to return to the office, and major events, like the New York Auto Show, being cancelled, all with a knock -on effect on businesses. Reintroduction of face masks in some areas is also unnerving consumers. Vaccine hesitancy and breakthrough cases are both plausible causes of concern.
Policy makers are alive to the threat Delta could be for the overall economy. At the recent meeting of the US Federal Reserve, Chairman Jerome Powell noted how they were monitoring impacts on restaurants and workplaces. The Fed’s current view is that this is a manageable risk, but slow-downs in vaccination rates are a worry. Generally most current economic forecasts don’t factor in a Delta variant knock to the 2021 picture, so if we see a continued upward drift in cases, we could see a wave of economic downgrades.

It’s clear we will see a loss of momentum in the US economy in the second half of this year – the question is how much.

Financial markets naturally are very focussed on whether the outlook is more towards Fire (surging inflation, higher interest rates) or Ice (slowing growth, undermining profit forecasts).

Economists seem quite divided.

However the general population is more clear on where the risks are. A survey by Monmouth University in New Jersey last week pointed to inflation being the key concern for only 5% of households, while Covid and the overall economy were the biggest concern for nearly 30% of US households.

And in terms of where the real risks lay – this seems about right.

Fund Management – Next Steps

It’s business as usual for fund managers – in fact it’s better than usual.

Recovering markets and consistent positive funds flows have pushed global industry assets under management to a new peak of €93 trillion. That’s up 11% on the previous year. Closer to home European asset managers saw their assets up 5% to over €25 trillion.

Investors both retail and institutional continue to add to their holdings. In Europe investor inflows in 2020 were over €750 billion – that’s the highest since 2014 and one of the highest in the last 13 years.

Two recent reports, well worth reading, from McKinsey and Accenture respectively, paint a generally positive picture.

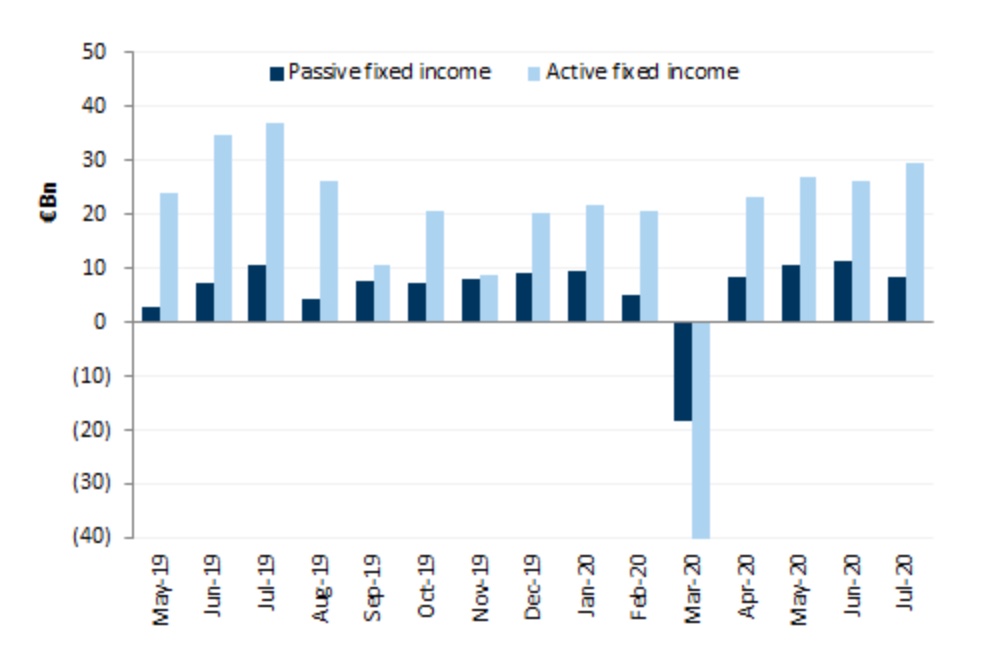
Most of the fund inflows have been into equities and this accelerated into 2021. Both Active and Passive strategies have made ground. The absolute size of flows into Active has been greater than into Passive. For example in June, active strategies recorded €21 billion of inflows compared to €14 billion for Passive. This still represents a greater momentum of growth for passive products, given the different size of the asset base.

And the asset management business is still very profitable. Despite continued pressure on fee income – down by 1/3 in last 7 years – fund management groups grew their profit margins again in 2020. There is continued focus on costs. Zero travel costs during the pandemic continue to be cited as a positive in many company annual reports. Looking at the costs of running the business compared to the income earned, this has been managed down to 59% from levels of 70% ten years ago.

Corporate activity in the asset management sector continues at pace. Globally, figures from PWC suggest that 2021 is on track to be a record year for M&A.
Ireland is no different. The last 12 months have seen a flurry of deals ushering in further consolidation in the domestic fund management arena. Increasingly the deal rationale is moving beyond just cost synergies. There have been several examples of large asset management companies looking to acquire financial planning and advisory operators to ensure great stability around route to market. This reflects a global trend. Ireland has also seen corporate activity as a fall out from Brexit as some players have opted to exit the market because of uncertainty and others enter, to ensure EU access. There has also been some regulatory driven activity which will see further changes in the Irish asset management landscape.

One fund management trend which continues to break records is that of ESG investing. In Europe overall, flows into ESG funds ballooned to EUR 233 billion in 2020, from EUR 126 billion the year before, according to Morningstar. Responding to investor demand, asset managers launched a record number of 505 new ESG funds and repurposed more than 250 conventional funds in the last year. Regulatory pressure and government policy continue to underpin this drive. This year fund managers need to categorise their funds in terms of ESG credentials further increasing transparency for investors. It is hard to see this reversing.

Increasingly ESG will become a “walk the walk” as much as “talk the talk” for fund managers themselves. Fund management companies will need to demonstrate that they operate to the same high ESG standards that they expect of their investee companies. Gender balance, rotating directors, environmentally rated buildings etc. at the fund management company level will matter for business development. The CEO of Schroders, one of the world’s leading managers, points to and welcomes this level of scrutiny on the fund industry.

And as the dust settles somewhat on this new landscape, expect to see a lot more investment in the brand by fund management companies. Practically all fund managers (97% according to the Accenture survey) see brand as a key competitive differentiator. Given the amount of change of names we have seen in the industry, the majority of companies believe they have decreasing brand awareness today. Allied to this will be a drive by many companies to ensure and promote their brand as fully aligned with best practice ESG principles. Expect to see a lot more investment in brand and brand awareness from the fund management industry.

While underlying profitability and trends were not really impacted by the pandemic, how fund managers worked, was revolutionised. Highly complex organisations moved 100% to a WFH structure smoothly and efficiently. It had been reasonably common already, especially in the UK, to accommodate “star” managers by allowing them to work remotely, whether that meant the Scottish Lowlands, York or Kensington High Street. The pandemic saw this now applied to marketing, client relationship, administration, finance etc.
The future is likely to be about striking a balance the need to coach, mentor and develop softer skills which may require office attendance; and the need to recruit and retain talent where some prospect of WFH would be a positive. Expect a “hybrid” outcome with perhaps a greater degree of structure than some might be currently imagining.

Irish Financial Services – can you trust them?

You can’t go the distance
With too much resistance

    Billy Joel, A Matter of Trust, 1986

Trust in Irish Banks and other financial institutions is on the floor.

And the disappointing thing is that in the last two years things don’t appear to have got any better.

And trust matters.

A 2021 survey across 28 countries and 59,000 customers revealed trust as the single most valued aspect in banking and it was ranked first across every single country surveyed. Bolstering this, a 2019 Accenture survey noted that globally consumer trust in financial institutions was “high and rising”.

Set against this, the Irish Banking Culture Board recent report makes for very difficult reading. The data was gathered by Edelman which is the global leader in measures like trust and reputation for corporates, governments, media etc.
This survey solely covered banks. While there is a battery of numbers, some stand out. 46% of respondents have low trust in banks compared to only 19% who would hold them in higher regard. This wholly negative outcome is at odds with a more positive view globally on banks – and by a wide margin.

And the momentum is going in the wrong direction.

Based on respondents aged 45 and over, only 18% feel that the sector has improved since 2008. 43% feel things have gotten worse.

The gloom continues when the survey looks at the role banks could potentially play in the current crisis. 73% of respondents believe banks should play a key role in re-invigorating the economy but only 38% feel they have, and that quite simply banks have failed to step up. This places it bottom of the pile for the sectors included.
.

Admittedly the data is nuanced. Respondents were slightly more positive when asked about their “own” banks as opposed to the sector overall. And younger people (up to the age of 24) were also less downbeat. However the younger age cohort is likely to have lower engagement levels with banks, have greater exposure to many of the disruptors in financial services, or simply a shorter memory.

The picture painted by the survey is not that surprising given the news-flow in the past 18 months in the broad financial services sector. We have seen continued fines in the tracker mortgage debacle, branch closures which can dis-enfranchise vulnerable clients, banks doing U-turns on refunding customers, court cases over pandemic insurance pay-outs, stock-broker fines and sanctions etc.

The challenge for those seeking to improve perception and reputation across this broad sector is how to combat headline risk. Headlines, quite often specific to one company, can have repercussions for the sector overall.

Trust is high on the agenda for financial regulators. Andrew Bailey, when at the UK Financial Regulator, made the point that trust is not just about knowledge or skill but equally about honesty and good intentions.

In Ireland, trust features as one of the five principals that the Central Bank works to in ensuring fair and transparent market place for consumers and counterparties in general – “vision is for a trustworthy financial system supporting the wider economy”.

Derville Rowland, Director General Financial Conduct, stated it most eloquently and managed to bring Confucius thought into the Irish financial regulatory landscape (I think for the first time!) concluding that “Without trust, we cannot stand”

Trust must be recovered and this will be a long journey. The Financial Regulator makes the point that a truer definition of compliance is more empowering and ambitious than perhaps our minimalist interpretation; a truer definition being more about accomplishing and achieving.

Given where we’re starting from, the IBCB and the sector overall has a truly great and meaningful opportunity, and taking account of the regulator’s more ambitious and aspirational casting of compliance, we should strive to make it not only about regaining public trust – but also respect.

Asset Management and ESG: Doing Good or just a Business Opportunity?

The numbers continue to amaze.

ESG (Environment/Social/Governance) seems to be everywhere in the investment world.

84% of flows into global equities in the past 2 years were into ESG funds according to one source. And there is no slackening in the pace –  flows in the last 4 months of 2020 were better than the previous 20 months combined.

The pandemic has lit a fire under these investment trends. 

And ESG is performing well.

2020 was a blow-out year for the S&P 500, but ESG funds did even better. Looking at the numbers for those firms who run both ESG and Non-ESG mandates confirms superior performance from the ESG mandates over 1 , 3 and 5 year time periods. This is a key part of the marketing message – you can invest on a sustainable basis without foregoing return.

ESG is likely at the top of every marketing budget, every fund launch calendar, every business development meeting agenda at major asset management companies globally.

It’s clear there is both a response to demand and a creation of demand.

ESG can be quite a complex space for investors to navigate, an alphabet soup of acronyms being added to on a regular basis. Added to this is the fact that ESG approaches vary considerably among asset managers.  

In February, the Central Bank of Ireland clearly laid out the risks in such a landscape where “strong investor demand is met by products purporting to be sustainable in nature but do not meet standards”. This is a global concern for regulators – the FCA in the UK expressed similar views. The FCA said  they will be focussed on the development and integrity of the ESG market and will examine ratings as well as qualifications.

There are a few things investors should look to in considering their ESG options. 

Examine the fund’s track record. There have been a few undercurrents in stock-market sector performance which have played to ESG mandates favour in recent years. Many ESG funds would be underweight or not invested at all in fossil fuels. This has been very beneficial, as the energy sector has been weak due to slower economies and pricing ill-discipline. This could reverse. Also many ESG funds have found themselves overweight in sectors such as technology, which have good ESG scores and have also enjoyed phenomenal performance, partly driven by Covid circumstances. These high growth sectors may be compromised if interest rates were to rise meaningfully. 

Also what period does the performance track record cover? It is important to point out that while many of the ESG labelled funds are new, some are simply a rebranding of already existing funds. According to Morningstar, over half of ESG funds were already in existence but have now been converted to sustainable funds. This is important for a number of reasons. Firstly just how much a re-engineering of process etc. has really taken place? Also it means we may need to be careful in looking at the performance track record that the asset management company is showing.

The majority of ESG funds globally are actively managed. In this space active is about 4 times larger than passive strategies. 

It is vital to look at exactly what the fund manager is doing within their ESG process. Are they really engaging with companies on ESG issues and voting at AGMs? Recent surveys have suggested that some of the larger asset managers are less pro-active than they portray. And what about how investments get rated?  Are they simply relying on third party ESG scores or do they have an integrated ESG framework and in-house expertise. Regulators have cautioned against managers mechanistically following third party ratings providers. There are often inconsistencies as ratings providers have been known to rate companies differently. 

Important to look, as well, at the resources allocated to ESG within the asset management firm. What percentage of full time employees have they allocated specifically to their ESG endeavours? For large European asset managers this currently ranges between 1 and 4%. 

Questions around integrated investment process and numbers of FTEs working on ESG, are really about commitment and conviction,  Both these factors appear linked to superior investment performance.

The European Commission has established an action plan on sustainable growth investment. The most recent instalment being the SFDR guidelines. These will require fuller disclosure of the degree to which ESG factors bear on the investment outcome. Hopefully this should help crystalise many of the issues for those considering investment.

Double Dip

While we may gaze enviously at the pace of vaccine roll-outs in the UK or the US, so too might the European economy look enviously to the US at its pace of  economic growth in the face of the pandemic.

While economic forecasts are being revised up for the US, with some now suggesting a strong first quarter and 8% or more for the year as a whole, here in Europe we are likely facing into a double-dip. 

We came out of 2020 with a negative Q4 and it is now looking like the current quarter will also be in the red. We have seen the EU Commission reduce its economic forecast for the full year and push out the recovery phase more into 2022.

We shouldn’t be surprised.

We are still in the grips of a pandemic and many economies are as closed as they ever were in 2020. Fears over a third wave are in fact leading to increased lock down measures in Italy, France and elsewhere. Looking at Covid-impacted sectors (transport, education, construction, etc.) current activity levels in Europe are 63% below where they were pre pandemic. Lock-down stringency has been increasing across Europe since the end of October and as current actions show, isn’t easing soon. 

As an example, air traffic in Europe currently is tracking at around 20% of 2019 levels. But in the US, that figure is up to 50% with over a million people boarding planes every day on average. 

Some market forecasters are fearful of the US economy actually overheating. Bond investors have become increasingly skittish. And the path of the recent Covid relief package through Congress wasn’t easy, as many Republicans view the economy as doing just fine. They see little need to fuel the economy even further.

Why the vastly different experiences on either side of the Atlantic?

A stuttering vaccination programme in Europe isn’t helping. The US, which had lagged initially, has now 13% of the population fully vaccinated, which is better than what Europe has achieved for the first dose alone.  Supply issues and efficacy concerns have dogged the European roll-out. While there will likely be some catch up as vaccines become more plentiful, this still pushes the collective immunity threshold date further out – perhaps beyond the summer. This then becomes time critical for those European economies who depend a lot on tourism. Tourism related activities account for 11% of GDP in Southern Europe and France and 17% of total employment. If tight restrictions, similar to current, are in place to the end of Summer, it will knock a further 1-2% off GDP and be felt most in Spain, Italy Greece and Portugal.

The other driver of the economic gap is quiet simply that governments like the US have just spent more. Looking at the amount of fiscal support relative to the size of the economic implosion that we saw in all economies, the big spenders were the US, Australia and Japan while spending in Europe was substantially lower as a percentage of GDP. And this is before the most recently agreed Biden package – so the US will surpass all major economies. This support will help generate a strong economic recovery in the near term, though will have to be financed at some point in the future.

The European economy may well emerge from this soft spot and see a lift off from Q2. It’s all really down to the numbers and the battle between the vaccines and the variants.

At that point, other factors may kick in to spur growth, such as a sharp boost to consumer spending as pent up demand meets excess savings. European banks have seen a near €600 billion increase in consumer deposits in the past year. Tourism would be a major beneficiary of such spending.

Still, the most likely outcome for 2021 is that growth in the US economy will be well over double what we get here in Europe.

A World Divided

The global economy has reached a fork in the road.

This is the advice the IMF provided to the recent G20 meeting of Finance Ministers and Central Bank Governors.

As the world continues to climb back from the worst peace time recession since the Great Depression, the prospects and pace of any recovery are, in the IMF’s view, “diverging dangerously across countries and regions”. 

The question is will policy makers in the major economies  take any action to prevent this great divergence.

Looking at global GDP figures masks the problem. The global economy is recovering and we will see economic growth of close to 6% this year and in excess of 4% next year – but it will be a very different journey and experience for the advanced economies compared to the lower income developing nations.

The numbers are stark. 

The IMF estimate that the major economies will recover to be only 13% below their pre-crisis levels at the end of 2022, compared with 18% below for low income countries. However emerging and developing economies will be a full 22% shy of their pre-crisis GDP. 

This could throw 90 million people into extreme poverty. 

This is the first reversal in over 20 years and the worst setback to the first of the world’s Sustainable Development Goals. Developing economies would fall behind again and income inequality increase, undoing years of progress.

There is little surprise in why the forecast economic recovery will be so uneven. Vast differences in vaccination timelines and varying abilities and willingness to provide policy support are key. 

Vaccines are likely to become widely available in G-20 advanced economies and some emerging market economies in 2021. But for the rest of the world, broad coverage for vaccinations is not expected until 2022 or later. Early inter-actions on Covax, the global initiative to ensure vaccine access, such as withdrawing stocks or insisting on domestic demands having priority, doesn’t give much heart.

Differences in how much governments were able to provide support is the other key factor. Decisive policy support, both fiscal and monetary, in G-20 economies has helped to prevent worse outcomes. G-20 governments have provided US$ 14 trillion in crisis related fiscal support. This has provided businesses and individuals with the necessary liquidity and credit to stay afloat, limiting the damage to economies’ productive potential. 

The level of support has been such that in many G-20 economies, the number of corporate bankruptcies was lower in 2020 than in 2019! 

There has also been a clear link between what level of support governments could provide and unemployment levels. Government support has been instrumental  protecting the labour markets in European economies while elsewhere we have seen savage job losses in areas like Latin and South America. 

It was not a level playing field. In 2020, advanced economies spent 24% of GDP in fiscal support; for low income countries this figure was less than 2%

Pandemics do nothing good for inequality. Both within and across countries, it is the young, the low skilled, women, informal workers, the already marginalised who have been particularly hard hit. Prolonged unemployment erodes skills, while reduced access to education can have a life-time impact. UNESCO  estimate the 900 million learners are still affected by school closures today.

The IMF is highlighting how dangerous this economic divergence between advanced and developing economies is. But this divided world forecast is not yet our destiny -however it requires decisive concerted action from the G-20 countries.

The IMF identifies three priorities; accelerate vaccine roll out in poorer countries, step up support to vulnerable countries and continue the fight against the economic crisis at home. 

Whether governments are prepared to raise their heads over national parapets is the question.

But as Kristalina Georgieva, Head of the IMF notes in her note to the G-20 – the crisis is not over anywhere until it is over everywhere.

Is Investment Management the Weakest Link?

In mid-2020, the Financial Times asked the question was investment management the weak link in the current economic/health crisis?

The authors were thinking back to the role played by the banks in the 2008 crisis and the need to inject public money into a system which still hasn’t returned to being a growth driver. 

Now, the value of global asset management has grown to such a scale as to far outweigh the assets of the banking system – was it too at risk?

While we still don’t fully know the economic/human costs of the pandemic, at first glance, it would appear that asset management is performing well. In fact, what we have seen, is that many of the pre-pandemic trends have if anything been reinforced and reinvigorated.

The key signposts for the asset management business continue to be costs, consolidation and style.

Lower fees are by now a well-established trend in asset management. Investors today are paying lower expenses on average than ever before. 

The drivers behind this trend are well known; increasing customer awareness of cost, growth of cheaper passive instruments, intensified competition among fund managers and in some cases changes in business model such as to fee based rather than commission based.

On average fund costs have declined by 30% since 2013. 

Morningstar provide a wealth of data on fund costs and flows. While all funds, on average, have reduced fees, the passive fund industry has led the charge with fee reduction twice that of active funds. Research suggests that low cost funds have a better chance of surviving and outperforming their more expensive peers.

In short this trend to lower management costs seems well-established.

Another fundamental trend in asset management which wasn’t derailed by the pandemic was mergers and acquisition. 2020 was in fact a banner year both in terms of number and value of deals done. Far from the pandemic choking off activity, the value of deals done in 2020 was 30% up on 2019. The reasons remain constant – the drive for scale to deliver synergies, being able to spread compliance and governance costs over a wider base, the need to broaden out a product offering.

While on a global level, activity has been among marquee names like Morgan Stanley, Franklin Templeton, Legg Mason etc., we have also seen a pick-up in acquisition activity in the asset and wealth management business here in Ireland. The drivers have been similar to the global arena such as access to distribution, and increasing AUM to cover the ever increasing regulatory costs. Brexit has also sparked activity in the asset management sector as some UK firms were faced with the decision to invest further and incur more costs if they want to maintain a presence in Dublin.

We are likely to see further acquisitions in this sector, with the only voice that rarely gets heard being that of the customer.

Other established trends in asset management continued through 2020.  Flows to passively managed strategies outpaced active by a wide margin. In the battle of style, Growth was substantially superior to Value based approaches, apart from a brief respite in November. And interest in, and flows to, ESG mandates was stronger than ever. ESG investing now has a strong tail-wind of regulatory support, which will see assets under this umbrella continue to expand in coming years.

However at the coal face, there were some standout differences in how investment managers went about their work in 2020. In Europe and the US, fund management companies along with other financial service industries simply went “home”. Now some star fund managers (usually those who had the performance track-record or AUM to demand it) already rarely set foot in the office, but for whole firms to be out of office on this scale was simply revolutionary. Fears over systems, compliance etc. seemed unfounded. As McKinsey point out there have been no major publicly reported breakdowns in technology or back offices at large asset managers, even with as much as a reported 98 percent of employees working from home. This will have impact into the future.

One other change in asset management has been in the area of client contact or business pitch. In the world of “Zoom”, that all important first presentation or one- on-one meeting is clearly less substantial. The ability to build up trust and confidence with a new client is compromised. 

In a competitive situation, this plays into the hand of the incumbent, where the people, values, systems etc. are already known. 

Large diversified asset managers already in place are at an advantage. In US asset management, 80% of new business has gone to 10 firms in 2020. 

So one of challenges for asset management in 2020 has been selling new business to new clients.

The Financial Times can be reassured that asset management is notthe weak link. The industry has been more nimble than perhaps it knew.

But there have been changes in how business is done, especially around the competitive dynamic, which may not be temporary.

The End of Interest Rates

Interest rates are the policy tool of choice for Central Bankers.

And until the Great Financial Crisis, they were almost the only tool investors paid any attention to. 

This was how Paul Volcker, then chairman of the US Federal Reserve, whipped inflation out of the US economy from the early 1980’s. Setting interest rate policy was how newly independent central banks were able to align their inflation goals with the business and economic cycle, as opposed to the electoral cycle which may have suited politicians more. 

Monetary policy, with all its lags, was still how policy makers responded to the LTCM crisis and the early stages of the Great Financial Crisis. 

However we have now grown accustomed to the unconventional becoming conventional.

Tools such as asset purchases are now a core part of the Central Banker’s armoury.

Partly this is a result of just how much the interest rate lever has been applied. In 1979 interest rates in the UK were 17% compared to 0.1% today. We are at, close to, or below zero in so many major economies. 

And now the issue becomes apparent – can more cuts to interest rates work?

This issue is known as the “Zero Bound”. Pushing rates much lower will not stimulate the economy in “minus land” as it would in more normal circumstances. Interest rates cannot continue to go negative  – investors would simply opt to hold cash – notwithstanding security and storage issues. Minus rates also undermine the banking system as an unwillingness to pass on negative rates to the retail base hits profitability.  This ‘Zero Bound” issue with negative interest rates  reduces their effectiveness as a Central Bank weapon. 

So if rates can’t go down – can they go up?  

Deep down in their monetary soul, central bankers like higher interest rates – simply because it allows them to cut rates if required to boost the economy. It is about keeping their powder dry.

The problem today would be the journey to those higher rates. A defining characteristic of the global economy and global corporations today is the sheer level of outstanding debt. 

Government debt, even pre-Covid, had been high; but increased spending and lower tax income has pushed it even higher. The Congressional Budget Office (CBO) in the US expects government debt to go to 200% of GDP by 2050. In the UK, similar forecasts, from the Office for Budget Responsibility (OBR) are for public debt to go from £2 trillion to £3 trillion by 2025. Other European economies are even more indebted as are a large number of Emerging Economies. 

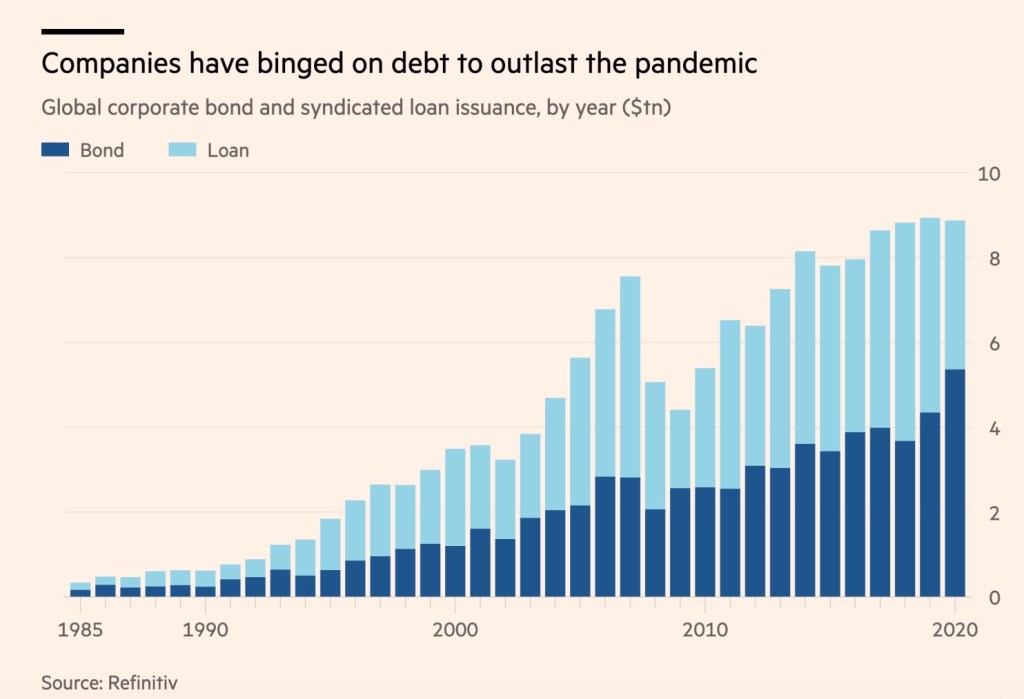
This debt build-up has been mirrored in companies, where corporate treasurers have been quick to load up on what in the past few years has been exceptionally cheap debt through the corporate bond market. Companies went on a borrowing binge in 2020, as they faced into sharp declines in business activity  Global corporate debt issuance surged to $5.4tn, a record high and over 20% more than the previous year. Companies also tapped the syndicated loan market for a further $3.5tn. Coupled with the downturn in profitability for much of the corporate world, the borrowing spree has driven up leverage ratios to all-time highs. The ratings agencies view balance sheets as increasingly unstable and forecast a rise in corporate defaults and in the number of “Zombie” companies, where interest payments exceed profits.

The IMF estimates global corporate debt at $20 trillion and has labelled it as a “ticking time bomb”.

This level of indebtedness amplifies any impact we could see from higher rates – a bit like the “away goals” rule in soccer. This is not an environment for aggressive rate hikes!

Higher interest rates can now been seen as a systemicrisk given the abundance of borrowing by both public and private sector. Central banks increasingly take into account the feedback loop from the financial system to the real economy in their policy actions. This underlies the comments from so many central bankers that higher rates are far out on the horizon. As Kristalina Georgieva, Managing Director of the IMF, noted there is a “very, very high probability that they will stay low for quite a long period of time.”

We can also see this in the more flexible attitudes to inflation that many Central banks have taken, and indeed why a number of leading central banks (including the ECB) are reviewing their overall monetary policy framework. 

As Central Banks review their policy frameworks and the tools they may select in the medium term, such as asset purchases, forward guidance and macro-prudential policy, interest rates are not on the menu. 

What investors are buying now

Investors ran for cover in March, as financial markets swooned in the face of the oncoming pandemic, and in some areas we saw significant selling of investment funds.  As markets bounced back in April and May, we saw a full reversal of those investor outflows. The ebb and flow of economic and public health data have influenced markets since then. And while we know that individuals have increased their overall savings and deposits, they have generally continued to add to their fund holdings through the subsequent months – though what they have been buying has changed.

While investors did buy back into equity funds in the immediate aftermath of the sell off, the experience since than has been somewhat patchy according to data from the Investment Association. Equities have been the clear “risk-on” asset, and when there have been concerns over vaccines or when renewed lock downs have threatened economic growth forecasts, we have seen investors reduce their equity exposure. We saw this in September for instance when many investors, certainly in the UK, sold out of equity funds.

What has also been interesting, in equity fund flows and performance, has been the type of stock that has been working for investors and fund managers?

For most of this year, the darlings of the stock market have been the high growth names like Amazon, Google, Netflix etc. As well as partly benefitting from lockdown conditions, they are also less dependent on near term GDP forecasts– theirs is a long term investment case. So investment funds that were in this “growth” category did well and their counterparts that would be labelled as “value” stocks continued their long term relative decline. So far this year US growth names have 36% better than value. And over 10 years, the annual return from investing in US Growth stocks was 18% compared to 10% for value names. However in November on the back of the Biden victory and the news on a possible vaccine, value investors (and funds) had their day in the sun beating their growth counterparts. Though at time of writing the gap is modest  value stocks are up 11%, compared to an 8% return for US growth investors so far this month.

Is there going to be a change in market leadership and winning investment styles? Too soon to say, global economies are still fragile and vaccine- dependent . Worthwhile keeping an eye on bond yields as low yields play a key part in supporting the valuation of these long term growth stories.

Other asset categories have been attracting investor attention recently.

Bond funds have seen significantly more inflows than equities, based on fund data in the UK and data from the Central bank of Ireland.  And while traditionally this might have meant boring domestic government bonds, because today they offer such low yields, the key words for bond investors have been global, corporate and strategic. 

We have seen more investment in corporate bonds as investors seek to eke out some extra income. This usually means not only investment grade bonds but also high yield bonds – some of which in the past would have been labelled “junk”. 

As well as moving up the risk spectrum on corporate bonds, there has been steady interest in “strategic” bond funds. This is where the fund manager has a wide and active brief that will allow them to deliver a return in excess of cash through potentially investing in a range of bond types and markets – including Emerging Market bonds and currencies. 

To date corporate and strategic bond funds have certainly had a strong tailwind at their back – Central banks have become buyers of corporate bonds. But they are not riskless assets and we have yet to see a major credit event that might have knock on impacts on poorer quality assets.

As well as the bond story, another big feature in what investors are buying in 2020 is in the area of ESG investment. These are funds that look beyond the balance sheet and the P&L account to invest in companies who score well on issues such as good governance, good social practices and environmental policies. 

This is a global phenomenon. In the US according to Morningstar, last year in  we saw $21 billion flow into the sector. This year it is over $31 billion already. In the UK 2020 flows are four times what they were in 2019.

Investors have bought into ESG funds through 2020 regardless of underlying market conditions. In March in the face of industry-wide outflows,  ESG funds still saw money coming in! According to Investment Association data this sector saw positive flows each and every month.

So as well as selling very well, these funds appear “stickier” as the underlying investor is motivated by more than just market beta. There is a very wide range of  ESG funds now available in Ireland and given proposed regulatory changes, notably on the pension front, we will see continued meaningful investor demand. 

I suspect that demand will be met by fund supply!

Visibility getting better – but companies aren’t waiting.

Company CEOs have been finding it difficult to provide guidance and clear business outlook in 2020 given the uncharted waters, but it’s been getting slightly better. Earlier in the year during the Q1 reporting season, almost 70% of US companies that normally guide analysts and the markets on what to expect, simply abandoned giving any forecasts. Naturally enough, this was most evident in areas like consumer discretionary. For Q2 this number had improved a bit to just 52%.
It is likely that even more companies will be able to give guidance on business prospects in the reporting season that’s currently underway.

This will still be a shocker of a reporting season with profits down 15-20% on the prior year – second largest Q3 decline since 2009. However it may not be a huge negative surprise for markets as analyst expectations have already been battered down. However in a quarter which will be dominated by politics, worsening pandemic impact and the stop/go progress of vaccines, if there is some greater clarity over company profits, it may be the only hard news investors get.

As in previous reporting seasons this year, it is less about the numbers and more critical to listen to what CEOs and CFOs are saying, to gain some insight into corporate confidence.

What is very interesting now is how many companies have moved already to re-engineer their business models to deliver better profits in a post-covid world.

Nike was quick out of the blocks with its own quarterly numbers, which are on a slightly different schedule than most companies. The Oregon-based sporting company delivered good numbers with sales around the same level as the previous year. This was a very solid outcome for one of the biggest brands in the world, and was achieved with a significant drop of 33% in its promotional spending, as so many high profile events were cancelled. Expect Nike to consider just how effective much of this type of spending really is. Can they spend less and spend better? We may well see fewer but more impactful brand campaigns. As Matt Friend CFO of the Oregon-based company said there will be a “sharper prioritisation” of such spending, and in guidance that was more qualitative than quantitative, for Nike “the future is bright”.

Self-help was also the key elsewhere. Darden, the US restaurant chain, who operate brands like Olive Garden and Long Horn Steakhouse, moved quickly to adjust to new circumstances. Supply chains were restructured, menus simplified and they made a significant move towards take- away business. Takeaway business was up 123% in the quarter. While they did cut back on marketing, it had less of an impact on sales than feared. So like quite a few companies are saying in their statements, marketing spend efficiency will be “re-evaluated”. Company CEO Gene Lee believes that as of today they have better visibility into their business model than before – and are better placed. As an indicator of just how effective these changes will be in making this a more profitable company into the future – Darden forecast that they can get back to pre-covid profitability at only 90% of pre-covid sales!

Even companies caught in the eye of the Covid storm are acting to transform their business model in advance of any better conditions. Walgreens, the pharmacy and general retailer, highly visible in most US cities, has been playing a key role in fighting the epidemic. They have completed more than 1 million Covid 19 tests at more than 440 sites in 49 states and have increased testing capacity to 500,000 per month. However at the same time Walgreen’s management have been transforming their business to deliver $2 billion in annual savings by 2022. They will close up to 500 stores, expand with drive-throughs and “kerb-side pick-ups”, and invest further in on-line. As result of their actions they see themselves coming out of 2021 “strongly”.

The pandemic has crushed demand for some companies and changed consumer patterns for others. But looking at what some management teams are saying in this reporting season, it is clear that resilient companies, who have used the opportunity to look at and refresh their business models, are going to come out of this on a more profitable footing.

China – 8 months on

China was the first major economy into the current pandemic and will be the only G20 economy to show positive growth this year.

The OECD has just revised up its view on Chinese economic growth for 2020 to just under 2%. Their previous forecast in June was for the Chinese economy to decline by 3.7% this year.

Now, 2% growth is far short of what we have come to expect from China in recent years, when numbers of 6% and 7% were more commonplace. But in a year when the global economy will slump by 4.5% as result of Covid 19, any positive economic outcome is a stand-out. Consensus economic forecasts for China‘s growth this year are in line with the OECD projection at around the 2% mark. There is also common ground around a 2021 forecast of 8% surge in the Chinese economy.

What got us to here?

It was January 23rd when Chinese authorities initiated a lock-down in Wuhan in a bid to combat the virus. Policy measures were severe. As measured by the Oxford University Stringency index, policy restrictions quickly moved to levels never seen in any other major country or region. However we began to see some easing from the end of March. The government prioritised factory opening where it was easier to maintain safety protocols. This relaxation was consistent through the summer, and increasingly was applied more widely in the economy. Today policy in China today has largely normalised.

In the past week we have seen retail sales and manufacturing numbers that are now positive on a year on year basis for the first time since the outbreak of the virus.

While analysts have often been sceptical on Chinese macroeconomic data, other higher frequency, on the ground ,data also supports this improved economic picture. Restaurant and take-away activity are close to pre-outbreak activity levels. Daily sub-way ridership is just 10% below 2019 levels. City traffic congestion continues to rise. Property sales in the 30 major cities are above 2019 levels.
In July and August imports of steel and aluminium rose dramatically to meet the higher demand from manufacturing and construction.

We have also seen a jump in Chinese exports in recent months, but this is very much related to the global pandemic and the surge in global demand for PPE (plastics, textiles, fabrics) which China can supply. In recent months exports have been up by over 3% compared to last year. Without the PPE demand, export growth would have been negative – reflecting the global slump.

There is further opening to go. In recent weeks, for example, the government has relaxed capacity limits in cinemas and on domestic flights.

If one of the characteristics of the Chinese response was severe and speedy lock-down, swift government economic support was also key. From early March, we saw a series of initiatives such as subsidised loans to farmers, deferring loan repayments for SMEs, reducing tariffs on critical imports and reducing social taxes for employers. SMEs account for about 80% of jobs in China.
Reserve requirements for banks were also lowered and interest rates nudged lower.
China has also been active in the realm of vaccine development. While none of its three potential drugs have cleared Phase 3 trials, the government has given the go-ahead for them to be used on an emergency basis. One is already being used by the Chinese military. The UAE has also given the go-ahead for a Chinese vaccine to be used on an emergency basis making it the first country outside of China to so do.

Analysts estimate that the economic impact on China of a successful vaccine by mid 2021 would be to add just 0.5% to growth in that year. This is less than the likely impact of a vaccine on other major economies. The growth impact of a successful vaccine would be more substantial in the US and Europe, where the pandemic is relatively less well contained. It could add 2% to European GDP and over 3% to the US economy in 2021.

According to the John Hopkins data, China continues to report a small number of cases but these are classified as “imported” – a vast improvement on levels in February and March. Coupled with an economy which, according to this OECD forecast, will be back to normal growth levels in 2021, this has to be seen as a solid result.

How are Asset Managers managing?

We see regular coverage of how different industries and sectors are doing during this pandemic economy. It’s obvious, for example, why airlines would be among the hardest hit as flights fall away, or why e-commerce names, such as Amazon, would benefit from the tailwind of changing consumer behaviour.
Investment managers in fact seek to profit from recognising and evaluating these trends in their decision making. It’s a reasonable question to ask how are these managers themselves and their industry doing.

How are the asset managers managing?

Investment managers make profits by charging a small percentage on the quantity of assets they manage. So the more that these assets can grow, the more revenue and profit achieved. The two main ways this can happen are asset markets going up, or managers being able to gather new business. Costs can be relatively fixed so the big attraction of asset management is its “scaleability” – profits can grow dramatically as assets under management rise.

There’s no doubt asset markets have been volatile in 2020 – collapsing in February but recovering materially from March onwards, and now in some cases making new highs. Looking at global equities as a proxy for overall asset values, we are, at time of writing, ahead on where we started the year. Other asset classes such as bonds have in fact posted positive numbers year to date. So far this has not been a long drawn out bear market eating into the value of assets under management.

This relatively benign backdrop has been supportive for the share prices of asset managers. We can see this in the performance figures from the US market. While the overall Financials sector, which includes Banks, has been hammered, the Capital markets sector, which includes asset managers, is actually in positive territory along with the market overall. And given that the overall S&P index has been boosted by the stellar performance of the likes of Amazon, Google etc. this is a very solid performance from asset management companies.

Sector Performance YTD
Asset Managers +1%
Financials -20%
Overall Market +4%

The picture is broadly repeated in the UK where the leading asset managers have comfortably outperformed the All Share index.

So share price performance reflects an industry which is holding its own.

So market values are better, what about fund flows, that other critical factor in profitability?

Based on Morningstar data, 2020 has been a year of positive flows for both equity and bond managers in Europe. There was a significant once-off outflow in March as markets stumbled, but every subsequent month has been positive and the lost ground fully recovered. This again helps asset management profitability. The picture is more nuanced in the US with bond managers seeing very strong inflows over the year but equity managers facing asset losses. For active equity managers, this was merely a continuation of a well-established trend as they lose out to passive products.

Earlier in the year, there were some dire forecasts on the outlook for the asset management industry – job losses of 15% or more, cuts in compensation. This was based mainly on market volatility and what was seen as a “challenging” marketing environment.
The market rebound and continued positive fund flows have taken the edge off the gloom and doom.

Some management groups have looked to take opportunities of the environment. One large wealth manager in the UK is hiring an extra 100 financial advisors but also laying off more or less the same number in order to “up productivity” levels.
Other managers have noted how they benefitted from unanticipated cost savings. Schroders noted at half year that their travel and marketing spend was lower by £15M, as they simply travelled less!

Other broad trends remain in place over the past year despite the pandemic;

Flows into ESG products remain robust

*Mergers and acquisitions remain central to many corporate strategies e.g. Liontrust, Franklin Templeton

*Passive continues to win over active, especially in the US

*Institutional business continues to be more stable than retail.

*Asset management continues to be a very attractive business (favourable demographics, savings requirements etc.) and this hasn’t been derailed by the last 8 months.

However, remote working and the world of Zoom meetings may play a role in the competitive landscape. Certainly some of the softer, yet critical, issues such as trust and confidence are more difficult to address remotely. Peter Harrison, CEO of Schroders, noted last month the importance of having an existing relationship with the client, and being part of the “ecosystem”. He thinks it may be more difficult for challengers to establish new relationships.

Overall fund flows and financial market performance may be supportive for the overall industry.
But for asset managers maybe the challenge in today’s environment is less about overall business levels and more about the competitive dynamic, and how to win new business from a new client.

Markets, Media and Money Trees

Money tree

Every day in stock markets seems to be a tug of war between the medical facts and their implications for further lock-downs, and the sheer scale of fiscal and monetary action being announced, or in the course of being implemented.

We have had the juggernaut move from mid-March when global equity markets bounced by about over 30% from their lows mainly on foot of promised policy support. Now some like Christine Lagarde, the ECB chief, venture to say that we are past the worst in economic terms in Europe.
But in the US the medical facts are deteriorating, and we are seeing a pushback on economic opening, certainly in the sun-belt states. The response from authorities has been closer to lock-down than the surgical and targeted moves that John Hopkins University and others were suggesting, and markets may have been assuming.
And in the US on down days there are many examples of highly recognizable corporate disappointments to enhance the negative narrative. Today it was Harley Davidson and Walgreens.

For the media, it has always been clear at sector level who were the clear losers from the Pandemic. As the virus spread and its economic consequences clarified, airlines, restaurants, leisure, hotels all garnered headlines. Factset have produced interesting analysis on media trends and the medical facts. Tracking media sentiment against confirmed cases in the US shows somewhat of a broad-brush approach in the early days of the pandemic. For example, road and rail gets similar sentiment as hotels and restaurants. But as time goes on, and we get further information on the degree of financial distress in certain sectors, coverage gets more “nuanced”. As cases declined, many of the sectors in the firing line did see an uptick in positive media coverage. However Airlines continue to be covered by the media with a healthy dose of scepticism. Given the likelihood of continued travel restrictions, quarantines etc. that cautious media sentiment seems appropriate. One recent anomaly in the US has been much improved sentiment for Hotels and Restaurants despite only more gradual improvements in restaurant reservations (OpenTable). This may be a reflection of more casual dining as consumers begin to dip a toe in the water.

The sheer size of the fiscal and monetary response is what many look to in order to frame a more constructive outlook for stock markets. The numbers are huge – estimates of £190B in the UK,€750B in Europe and a Washington Post estimate of $6 Trillion in the US when you combine both the Federal Reserve and Congress. The IMF estimate that the fiscal response worldwide is close to $11 Trillion. The actions certainly provided the “shock and awe” that markets needed in March and April.

Global Debt Chart
However as the time frame lengthens, some of the media coverage around these packages is more about when certain supports will be reduced or stopped.
All acknowledge that unprecedented support is required and that debt to GDP ratios globally will balloon. The IMF estimates global public debt will reach 101.5% of global GDP – the highest level in recorded history

Not surprisingly, there is some mention of the fiscal responsibility side of the coin, that somewhere there is a limit to what can be brought to the table without compromising future generations and future growth. As the head of the Irish Central Bank, Gabriel Makhlouf said last week – “There is no money tree”.
However the media is giving much more space to outlining the scale and range of government spending. Indeed media coverage would be more supportive of the view of a former Irish Central Bank chief, Patrick Honohan, who said last week “There must be no loss of nerve in fully deploying the financial resources of the state and its borrowing capacity.”
And certainly for the economy and the markets that would seem to make sense.

Scarred. What the Pandemic means for inequality.

SeeSaw

The numbers amaze. Economies stopped and now as we get new data coming off such a pulverised base, the percentage growth numbers can dazzle on the upside. This can take forecasters by surprise – recent jobs numbers in the US are a good example, as are UK retail sales.

Economic growth is a good thing – very good. But hard as it might be, the focus needs to be on the quality of that growth as much as the quantity.

On issues such as sustainability or climate change, this does seem to be taken on board. There is a clear green tinge to many public investment initiatives. Governments have been made aware of the demands of the public, especially the younger cohort, for a clear green agenda in practically all sectors. The Swedish government’s attached conditions, regarding carbon emissions, in a recent financial injection into the airline SAS, are an example of how the emergence from the pandemic will have a greater sustainability imprint.

However there is another aspect where we need to be vigilant and that is the issue of income inequality.
Inequality in income distribution in countries and across countries already was a severe and growing problem. There are clear social consequences from the trend. But the other aspect of this is that quite simply it slows economic growth, leaving permanent scars.

Every pandemic in the twentieth century has led to increased income inequality.

Covid-19 has disproportionately hurt disadvantaged groups. While many people have been adversely hit by the health emergency and government mitigation measures, those with a lack of savings or insurance are impacted the most by a sudden loss of income. Workers in the informal economy with weaker job attachment or those in low skilled service sector occupations also bear brunt of the lockdown. In the developing world employment numbers for those with only basic skills fall by 5% over a 5 year period after a pandemic according to the IMF. Higher skilled workers and those with advanced education fare much better.

Educational prospects are severely impacted by the global lock down. The United Nations estimates that more than half a billion children have lost their access to education through this period. Lack of internet access and lack of appropriate devices is a significant factor in this, and according to the UN, Primary school children have been most impacted. While a concern globally, with potential long term consequences, it is especially a problem for emerging economies who face higher levels of “learning poverty” – an inability to read or understand a simple text by age 10.

Another feature of income inequality is that many people and indeed small companies don’t have full access to financial services and technology. Limited access to credit increases vulnerability both at individual and company level when cash flow simply stops. This leads to job losses and business closures which turns further widens the gap.
History shows that the greater the pre-existing inequalities, the more uneven is the impact of the pandemic. Income equality will hold back the strength and durability of growth.
In some countries the early experience isn’t great. In the US many of the financial measures aimed at lower income groups are set to expire in August – with little appetite from Republican politicians to extend. On the other hand a lot of tax breaks and provisions favour the already wealthy – according to a Congress Committee, 82% of those who stand to benefit earn at least $1m. annually.

We need a more inclusive recovery.

It is good that governments around the world have deployed extraordinary measures swiftly and will continue to do so, but the shape of that investment matters if we’re to prevent long term scarring of the global economy.
Healthcare and social protection need to be high on the agenda if we are to prevent the mistakes of history. Education needs investment with a view to ensuring wider access to the digital classroom. Failure here may cast the longest shadow. Access to high quality childcare must expand, which in some cases may boost female participation in the labour force and ultimately long term growth. It will be important to harness the power of technology in other areas as well as education. Financial inclusion can matter. If we broaden the access of low income households and small businesses to finance, it may be possible to smooth the experience during a cash flow shock. The IMF estimate that there can be a 2 to 3 percentage point difference in GDP growth over the long term between financially inclusive countries and their less inclusive peers.

Education, health-care, social protection, and technology should all be points on the compass as we navigate a path out of the down-turn. It would be important that there is co-operation and cohesion within and between regions. Policy measures, where they can, should be concerted and consistent.

That could be the challenge in a world where borders and minds may be closing.


Note: This article first appeared in the Sunday Business Post.

Beyond GDP. Using other measures to fine tune our exit from economic lock-down.


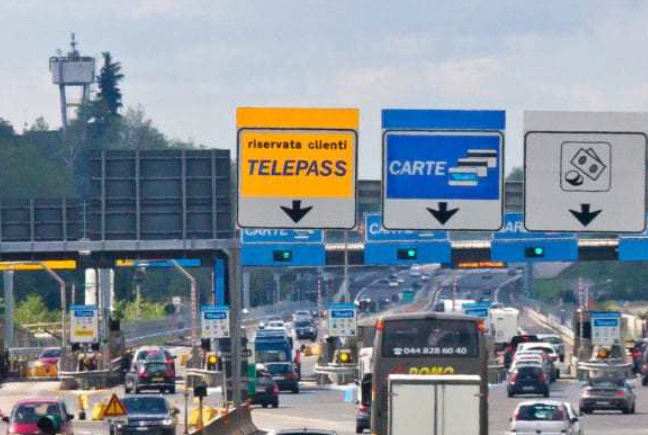
Toll Picture

At this point in the pandemic, what becomes very important is measuring the extent of economic revival as economies across the globe look to reopen and map any impact on the spread of the virus.

Being able to measure economies is tough at the best of times but given the size of the shock and the wide extent of the dislocation, it is now especially challenging. Most economic numbers, like GDP or unemployment ,are backward looking or lagging and tend to tell us how things were rather than how they are. And indeed most of the headline grabbing economic figures are subject to subsequent material revisions.
Survey data from both businesses and individuals, such as PMIs and consumer sentiment , can be more timely, but can be heavily influenced by the psychological shock of this epidemic. For example, looking at survey data in Europe last week, it has come out materially different from market expectations in both positive and negative directions. While we are this close to the outbreak, it is likely to remain “noisy”.

Now more than ever, we need to have robust and timely measures of how we are doing.

The IMF has recognised this and highlighted how useful other indicators may be in framing a view. These can be more frequent, more timely and more robust than say GDP calculations, if perhaps a bit unconventional. Included in these indicators could be electricity consumption, traffic count, HGV journeys, metro footfalls, weekly retail sales data etc. While they do require care in interpretation, they can also provide a good picture of underlying real economic momentum – and in a timely manner.

So how are we doing?

Some indicators don’t surprise. Air travel in Europe, as we know, has basically stopped. But it has been on an upward trend in China since the beginning of April and in the US from about two weeks after that, reflecting easing of conditions. The pace in the US has especially picked up in more recent weeks.

More generally in Europe we have seen a gradual pick up in mobility, road traffic, car registrations and retail sales albeit from very depressed levels.
This higher frequency data also highlights the gap between different European countries, with a relatively more robust north and a trailing south. Traffic through toll roads in Italy and Spain, at its low point in late March, was down 80% on a year on year basis, but has recovered to being “only” 50% down. By contrast truck traffic in Germany is much stronger at just 5% below its level at the start of the year.
Electricity usage is comfortably past its low in most countries but with Italy showing the greater pace of pick up in recent weeks.

Car registrations in some countries have improved quite dramatically in recent weeks. In Spain from a level of zero at the start of April, daily car registrations are now running at a daily rate of about 4000. The average through 2019 was about 6000 on a daily basis. France also has seen some momentum here with the most recent weeks running at about 80% of last year’s level. Clearly, there is a replacement cycle and pent up demand issue, but it still represents big ticket spending by the consumer.

One of the more unusual items now being focussed on is global maritime data from the Automatic Identification System (AIS) – basically ships’ radio signals – to show how international trade is being affected by the pandemic. Analysts can see if activity is picking up, is it finished products or commodities and what are the destinations? This trade data is available daily and in real time while official statistics can be delayed by weeks.

One encouraging sign has come from looking at internet data – and this has been pretty similar across the major European countries. Since the start of May we have seen a significant uptick in the level of internet enquiries into holidays and holiday accommodation. The level is still way off what we would have seen at the start of the year but perhaps a sign of improving confidence.

This non-traditional higher frequency data can, in the view of bodies such as the IMF, complement the official statistics especially at a time when we may see disruptions to the data. In many examples the focus is on level rather than growth rate which is important because we are still so far off normal levels that percentage changes can be misleading.
The verdict on this recovery so far – it’s started but uneven across regions and sectors and certainly not V-shaped.

This article first appeared in the Sunday Business Post

What’s going on? Forget the numbers What are CEOs saying?

Business Numbers


So Q1 was a write-off and there is zero visibility on business outlook.

But I believe there is value in looking at what CEOs, the people who actually run companies, are saying, to get a better sense of any unique or emerging trends within the downturn, and whether these trends may persist.

As of this week, we’re about 25% through the S&P 500 in terms of earnings reports. Normally this is a highly choreographed process with most companies beating the analysts’ forecasts, which the companies themselves have already had a strong hand in guiding. For the record, according to Factset, earnings to date are in aggregate about 5% below what had been forecast.

But the numbers don’t matter and guidance is cancelled.

In the face of the pandemic and the downturn, that’s the only honest response.

But we can look at the currents beneath this overall bleak picture. What are CEOs telling us?

Front line sectors, such as Airlines, are getting hardest hit. Oscar Munoz, CEO of United Airlines said that travel demand into 2021 was ‘essentially zero’. They flew 200,000 people in the last two weeks. The corresponding number for 2019 was 6 million – a decline of 97%. The company has cut its capacity to 10% of what it had previously planned. United see demand depressed into 2021, with one of the longer term impacts from the pandemic being less flying with more use of remote sessions and less business travel overall for what Munoz describes as “hand-shake” meetings. Cost cutting at companies will probably drive this also.

Coke is another consumer stock that saw its sales knocked but James Quincey the CEO sets a more positive tone believing that the back half of 2020 will see an improvement. The company has seen a 25% decline in global volumes this month alone – fully driven by the measures adopted by governments to tackle the pandemic. What Coke calls “away from home” sales – cinemas, sports venues etc. represent half the company’s revenue and have clearly disappeared. Home buying and “pantry building” (as Coke describe it) did not make up the gap and really it’s not that clear that it will in the near term.
It has been a similar picture for the management team at Heineken. Jan Francois van Boxmeer highlighted the 14% decline in their volumes in March and sees recovery being wholly dependent upon lifting of restrictions. Heineken’s response is to double up efforts on the retail side as they believe pubs aren’t coming back soon. So look for a bigger presence and profile from the likes of Heineken in your local supermarket!

Some company chiefs while not complacent, took more comfort from the resilience of their business model and less substantial exposure to discretionary spending. Arvind Krishna, CEO at IBM, while not giving guidance stressed the resilience of their customer base – 70% of their customers would come from healthcare and telecommunications – so perhaps less affected by the lock-downs and lack of travel. IBM focus on stress testing their business model and driving their cloud business. If business budgets were to be severely reined in, it would no doubt impact, but the message from IBM is; we’re not there yet.

Even companies whose products have been flying off the shelves look to strike a cautious tone in their comments. Mike Hsu, CEO at Kimberly Clark, maker of Andrex toilet rolls, spoke mainly about health and safety of staff and security of supply chain while acknowledging that their cash flow in the quarter more than double to over $700M. A degree of stock piling saw their global sales of toilet tissue up by 17% outside the US. Hard to imagine that was in their corporate planning assumptions!

Some company results highlighted the difference between the US experience and the more stark picture earlier in the year in China and Europe. Hershey,the chocolate manufacturer, pointed out how they had a solid start to the year, and in fact for the quarter as a whole saw reasonable demand in the US. However, chocolate demand in China declined by 8%. The company are alive to how consumer behaviour and social distancing protocols in the US may impact on their bottom line as the pandemic has spread. But as CEO Michele Buck pointed out, as a chocolate maker, their key “ability is to be able to make moments of goodness during this time when physical connection is limited.”(!)

One of the high profile names who has a better experience in this first quarter and gained a lot of attention was Netflix. They added nearly 16m subscribers, well over double what had been forecast. However there was little triumphalist in their letter to shareholders though, as they rightly acknowledged how tough the environment is for jobs and activity in the overall entertainment industry. The company notes how it is in a fortunate position and has contributed funds to support many of those who will find themselves out of work. Netflix also see a time, as home confinement ends, that their stellar subscription growth rate falls back – and they look forward to it!

It is very much a mixed tapestry of experiences for companies in the current situation and some are clearly more exposed than others. There is also a clear tone of corporate responsibility underlying a lot of what CEOs are saying. The speed and severity of the virus has impacted on all, but as many of the comments reveal – it may have taught humility but not helplessness.

What markets and managers are looking at now.

Turmoil

In recent days, the tone in stock markets seems to have changed from the panic tumbles on high volumes that we saw in mid-March. Volatility as measured by the VIX index has also reduced though still at elevated levels, but generally we have seen less of the 5-6% moves upwards and downwards on a daily basis.
A general read across what investment managers are thinking also suggests a degree of caution, though many are painting out what their exit strategy from the crisis will be, and how they will position portfolios accordingly for the ‘next new normal.’

The speed of the spiral downwards in markets is what many managers remark upon most, as well as the sheer scale of the monetary and fiscal action activated and proposed, that was required to stabilise markets at lower levels. Market moves reflected the ebb and flow of confidence that policy makers were alive to the seriousness of the issue. But now, governments and central banks have set their stalls out; and medical facts such as mortality and new cases have played a greater role in the past week. Political interpretations about those medical facts have played some role in market moves in the US.

Markets may scour the data for direction on a very short term basis, as we saw early this week, and we may see high frequency traders or hedge funds look to play. Given that the medical facts won’t move in a straight line, this means continued volatility, albeit at lower levels.

But large long-term investors are likely to look for clear, sustained, and meaningful improvements in the numbers to change their asset allocations to being more positive.

For investors, there are several features on the landscape that pose difficulties in framing or timing an appropriate investment strategy.

The actual degree of uncertainty in the current environment is unparalleled.
There is absolutely no clarity on economies or companies. For example, how bad will the US jobs market get? There is a very wide range of forecasts, with Goldman Sachs, for example, expecting US unemployment to peak in the third quarter at 15%. However at the same time, the Federal Reserve in St. Louis suggests a 30% unemployment rate is possible. It hit 25% during the Great Depression.

Forecasting company profits is even more problematic.
We simply don’t know.
Many companies have ceased making forecasts or giving guidance to analysts. Without such guidance, many analysts struggle to arrive at a meaningful number. Analysts have also in the past been slow to catch up to reality. At the start of the year, the average estimate from all analysts for company profits growth in the US this year was about 8% positive. Last week that estimate was -3%. But the final outcome, given falls in revenue and in margins, is likely to be an earnings hit closer to -30%. The sectors being hit the most include consumer discretionary and energy with consumer staples and healthcare holding up well.

It is clear that there is plenty room for shocks on both the macro and the individual company level.

Markets may also hold different challenges for different types of investors. Take the case of income investors – those funds that especially value the importance of dividend income in their investment process. This is a very significant group of funds in the UK for example. In an environment where many corporates will be starved of cash flow, paying cash out as dividends may put the overall enterprise at risk. So we will see certainly a reduction in dividends and in some cases cancelation. Regulators in the UK and Europe have urged banks and insurance companies to pause dividend pay-outs. Overall UK dividends are expected to be down by 50% and US by 25% in 2020.
Share buy-backs (which have been seen as a strong support for stock market levels) will go the same way. Many companies in the US have already suspended buy-back programmes and the expectations are that for the full year we could see a reduction of 50%.

Some investment managers fear a more inflationary environment in the future, as we may have supply constraints at the same time as fiscal and monetary policies stoke demand. While it could be an issue in the very short term, it is difficult to see inflation being top of the agenda. We know how long it takes for policy (especially monetary policy) to drive demand – the last six years of QE haven’t seen economies really take off. Also supply chains can be rebuilt. The experience from Avian Flu and SARS supports the view of little inflationary impact.

Given the overall and unparalleled level of uncertainty, it is not surprising that there is a range of views among fund managers. Some managers, such as hedge funds, may have very different time horizons and look to capitalise on shorter term market moves. Others may adopt very non – consensus views. One-UK based manager is using the Black Death of 1348 as their template for the timing and severity of the down turn. Most are somewhat less stark in their assumptions.

Broadly, investment managers at this point see the pandemic as a serious but temporary shock. They remain diversified and vigilant. A sustained improvement in the medical facts (fewer new cases), and some degree of visibility around corporate health, are what long term investors will look to, to frame the next stage of their strategy.

The investment risk is the same as the universal risk – as one fund manager put it: “a second wave of infections within countries that successfully controlled the first wave”. That would mean more drawn out economic contraction, more serious market impact and more overall uncertainty.


This originally appeared as an article in The Sunday Business Post on April 12 2020